
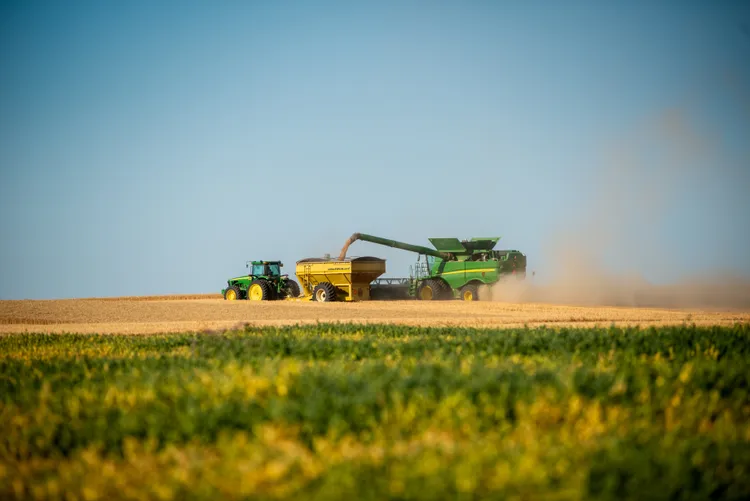
Milwaukee, Wisconsin: U.S. farm tractor sales fell 16.4% year-over-year in September, while combine sales declined 10.9%, according to new data from the Association of Equipment Manufacturers (AEM), signaling continued weakness in the North American agricultural equipment market.
The Numbers
U.S. dealers sold 15,024 tractors during the month, down from 17,979 in September 2025. Self-propelled combine sales totaled 369 units, compared with 414 a year earlier .
The downturn was broad-based across every tractor horsepower category. Sales of two-wheel-drive tractors under 40 horsepower dropped 15.4% to 8,952 units. The 40- to 100-horsepower category fell 18.7% to 4,443 units. Two-wheel-drive tractors above 100 horsepower recorded 1,396 sales, a 15% decrease. Four-wheel-drive tractors experienced the steepest percentage decline, falling 20.2% to just 233 units .
Year-to-date, U.S. tractor sales totaled 135,325 units through September, compared with 154,869 during the same period last year—a decline of approximately 12.6%. Combine sales reached 2,432 units nationwide, down 9.4% from 2,683 a year earlier .
Industry Reaction
“September’s sales underscore the difficulty in the agricultural market today,” said Curt Blades, senior vice president at AEM. “We approach this harvest season with optimism for increased certainty and recovery of farm economy” .
The figures reflect continued producer caution toward major capital purchases as farm margins remain under pressure. Large machinery purchases represent significant financial commitments, particularly when operating expenses, borrowing costs and uncertainty over commodity prices complicate equipment replacement decisions .
What to Watch
Producers and equipment dealers will be watching whether improved farm income, financing conditions or stronger commodity prices can slow the decline in machinery sales during the final quarter of 2026 . For manufacturers and dealers, weaker sales can create additional challenges as inventory moves more slowly and customers postpone upgrades .


